Simple Vacation Savings Guide for Seasonal Income Earners 2026
Following a simple vacation savings guide for seasonal income earners changed my entire perspective after years of unpredictable paychecks. Working seasonal contracts used to make booking any real trip feel completely impossible and irresponsible. You watch your bank account peak in summer only to drop dramatically by January. You do not have to spend your quiet off-season months trapped on your living room couch.
Calculate Your Baseline Bare-Bones Survival Budget
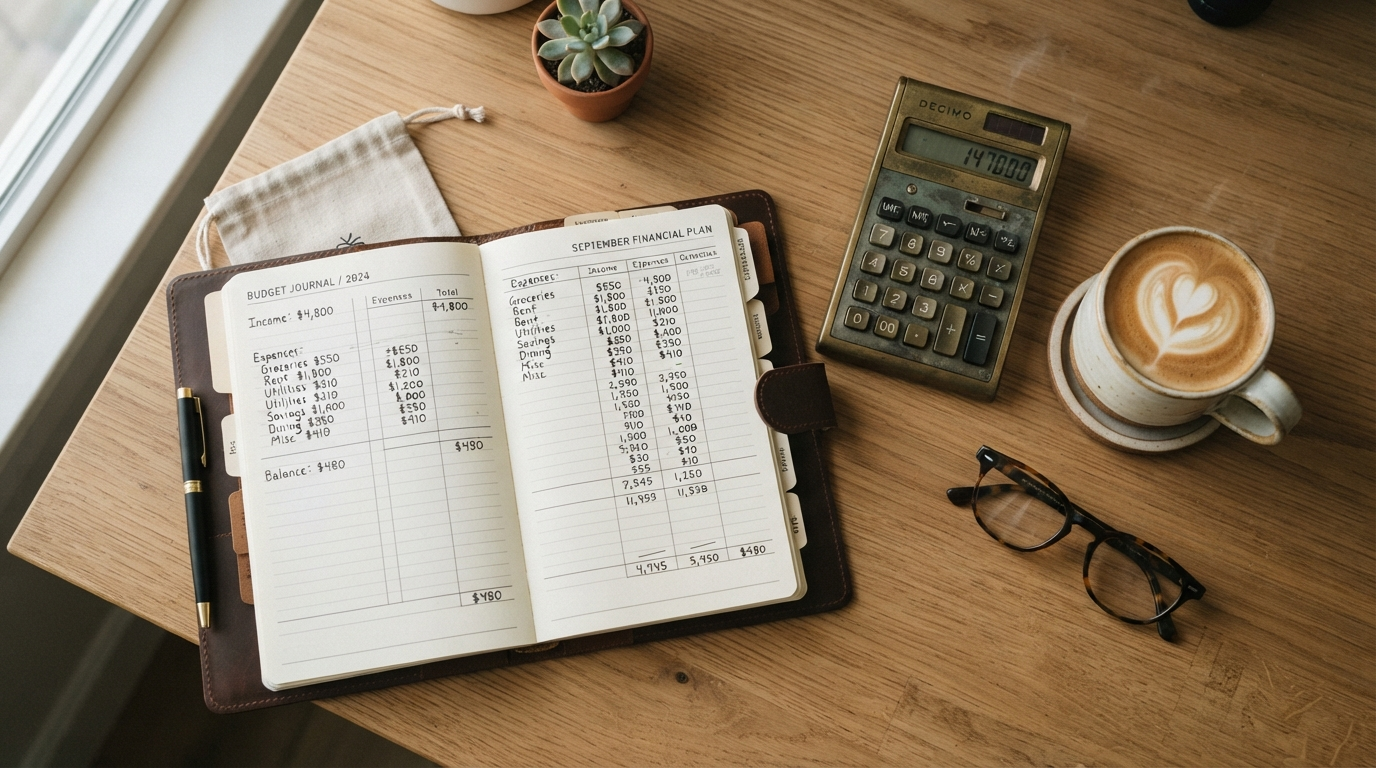
Tallying up your essential annual survival costs is the foundational move for anyone without a steady year-round salary. You need to calculate the exact amount required for housing, groceries, insurance, and utilities across all twelve months. Multiply your monthly core expenses by twelve to establish your mandatory annual baseline.
Subtracting this total from your projected peak season earnings reveals your true discretionary income. This calculation creates your bare-bones survival number and prevents you from spending money that should cover February rent. Knowing this clear dollar amount gives you full permission to allocate the surplus toward your travel plans without nagging guilt.
Establishing a Peak-Season Percentage Sweep
Relying on flat-dollar savings goals fails miserably when your paycheck fluctuates from week to week. Skimming a fixed percentage from every incoming check adapts naturally to the highs and lows of your busy season. When you pull a sixty-hour week with overtime, your travel fund gets a massive boost without squeezing your wallet.
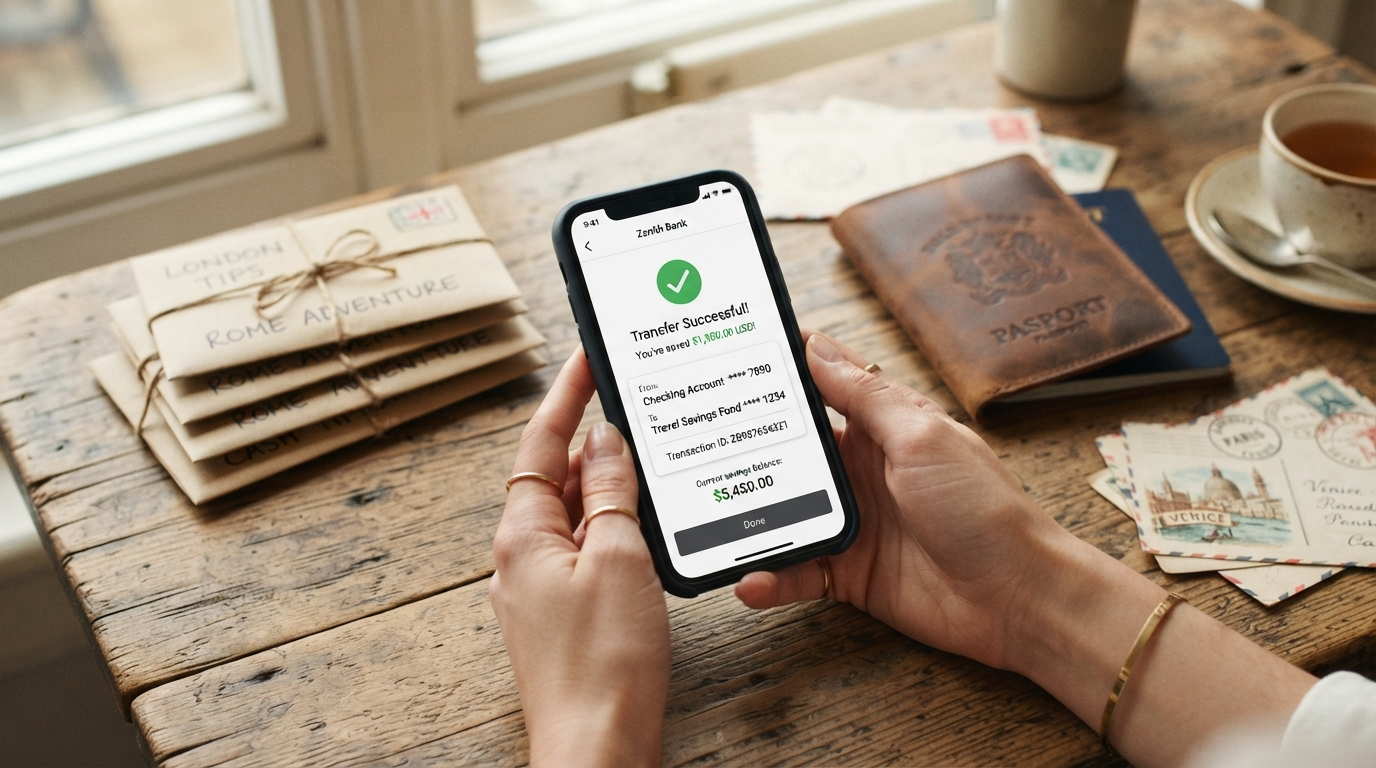
I set up an automated transfer that pulls twenty percent of every incoming deposit during my highest-earning months. Adopting this dynamic percentage sweep ensures your travel stash grows automatically in direct proportion to your actual workload. When a slow week hits, the percentage adjusts downward so you never feel financial pressure.
Also Read: Top Rated Travel Hacks for Tight Monthly Stipends 2026
Separating Your Travel Cash in High-Yield Vaults
Dumping all your earnings into a single standard checking account invites accidental spending on everyday conveniences. Keeping your vacation cash in the same place as your grocery money makes it far too easy to bleed funds during slow weeks. You need physical and psychological distance between your daily bills and your leisure money.
Moving your savings into an external dedicated sub-savings account at an online bank like Ally or Marcus creates that necessary friction. Following a simple vacation savings guide for seasonal income earners requires strict separation of funds so you never accidentally cannibalize your adventure money for takeout food. The modest interest you earn provides a nice little bonus for your trip.
A Simple Vacation Savings Guide for Seasonal Income Earners Managing Off-Season Cash Flow
Mapping your travel dates directly to your work lulls turns your irregular schedule into a massive superpower. Traditional nine-to-five workers are forced to travel during crowded, overpriced summer holidays and school breaks. Seasonal workers, however, hold the ultimate advantage: complete schedule freedom during quiet shoulder seasons.
Traveling during your industry downtime lets you secure bargain lodging and empty attractions around the globe. Booking during this off-season travel window stretches your saved dollars twice as far as peak-season vacationers. You get luxury-level peace and quiet while paying budget rates for flights and accommodations, IMO.
Prepaying Fixed Travel Costs During High-Earning Months
Purchasing your big-ticket travel items while your cash flow remains high eliminates stress later on. Buying your plane tickets, train passes, and lodging reservations in July means those costs disappear before your seasonal contract ends. By the time your slow season arrives, the vacation is already completely paid for.
Utilizing a structured prepaid travel strategy leaves you with only daily food and walking-around cash to cover during the actual trip. This prepaid approach represents a core principle in any simple vacation savings guide for seasonal income earners who want to avoid debt. You board your flight knowing you owe zero dollars when you return home.
Leveraging Seasonal Work Perks and Industry Reciprocals
Working in seasonal industries like tourism, ski resorts, and hospitality unlocks incredible hidden travel perks that most people never access. Many outdoor outfitters, resort conglomerates, and hotel chains offer reciprocal passes and deep lodging discounts for seasonal staff. You can often stay at partner resorts for free or at deeply discounted staff rates.
Ask your employer for an official industry reciprocal pass or partner discount list before your contract ends for the season. Swapping stories with fellow seasonal workers also reveals cheap housing swaps and regional insider tips you will never find in standard guidebooks. These perks make lavish mountain or beach getaways shockingly affordable.
Building a Buffer Cushion for Unpredictable Work Gaps
Unexpected weather changes, delayed seasonal openings, or early snow melts can shorten your peak earning weeks without warning. If your entire surplus sits locked in non-refundable vacation tickets, a bad season could threaten your basic living expenses. Smart seasonal savers always build a tiny safety cushion before finalizing leisure bookings.
Holding a modest contingency buffer fund inside your main account protects your vacation money from emergency raids. If work wraps up two weeks early, this cushion absorbs the blow so your travel plans stay completely intact. Maintaining this safety layer gives you genuine peace of mind while exploring new destinations.
Shifting from Fixed Monthly Savings to Dynamic Project Transfers
Assigning entire side gigs or specific high-tip shifts exclusively to your travel fund creates rapid savings without touching regular wages. Whenever you pick up an unexpected weekend shift, funnel the entire payout straight into your travel account. This creates a clear mental connection between extra effort and exciting upcoming travel rewards.
Enforcing this strict windfall allocation rule keeps your standard earnings focused on daily living and off-season survival. Applying these practical habits turns this simple vacation savings guide for seasonal income earners into an automated lifestyle you can repeat every single year. You work hard during the rush, and you reward yourself with authentic adventures when the work is done.
Frequently Asked Questions
How much money should a seasonal worker save for vacations?
Aim to save between ten and fifteen percent of your total seasonal surplus after fully funding your off-season living expenses. This ensures your basic bills are completely covered before you allocate cash to travel. A budget of one to two thousand dollars easily covers weeks of low-season travel.
What is the best vacation savings strategy for seasonal workers with irregular pay?
Use a percentage-based savings transfer rather than a fixed dollar amount every payday. Transferring fifteen to twenty percent of every check into a high-yield account automatically scales with your earnings. This protects your cash flow during slower weeks while maximizing your savings during peak overtime weeks.
Should I pay off all off-season debt before saving for a trip?
Maintain minimum debt payments and build a small emergency cushion first, but do not cancel leisure completely. Allocating even twenty dollars a week toward travel prevents burnout and keeps you motivated through grueling seasonal shifts. Balance is essential for staying sane while working demanding seasonal contracts.
How do I prevent raiding my travel fund during slow winter months?
Keep your vacation savings in a separate online bank with no debit card attached. Creating a three-day transfer delay between accounts adds crucial friction that stops impulsive spending. Label the account with your destination name to provide a visual reminder of what you are working toward.
When is the best time for seasonal employees to take vacations?
Travel during shoulder seasons right after your peak working contract finishes. Visiting tourist destinations in October, November, or April gives you rock-bottom lodging rates and empty attractions. Your flexible seasonal schedule allows you to take advantage of deals that regular office workers cannot use.
Conclusion
Managing irregular income does not mean you have to give up on exploring the world during your time off. When you plan around your natural earning cycles and prepay your expenses, travel becomes a rewarding off-season reality. Where are you planning to head once your busy season finally wraps up?



One Comment